Navigating 2025 Tax Changes in Romania

Navigating 2025 Tax Changes in Romania

2025 Romanian Tax Reforms

Are you ready for big 2025 tax changes in Romania?

Emergency Ordinance no. 156/2024 brings major updates.

These changes will change how we handle money in 2025.

The 2025 tax news in Romania is key.

It affects everyone, from small businesses to big companies. You’ll need a good plan and expert advice.

Tax lawyers in Romania are getting ready to help.

Our team of Romanian Lawyers and tax consultants is making strategies for clients to deal with these new tax rules.

It’s important to know about these changes to stay in good financial shape.

Key Takeaways

  • Significant tax rate adjustments across multiple sectors;
  • New microenterprise income thresholds implemented;
  • Income tax exemptions eliminated for specific industries;
  • Mandatory contribution rates reset for employees;
  • Construction and dividend taxes experiencing notable changes.

Understanding Romania’s New Tax Landscape for 2025

Romania’s tax scene is changing a lot in 2025.

This brings both challenges and chances for businesses and people.

The new tax rules come from big changes in laws that need smart tax planning and good economic forecasts.

Romania Tax Landscape 2025

The Emergency Ordinance 156/2024 makes big changes.

These changes will change how the government budgets and taxes different areas.

It’s key to understand these changes for good financial planning.

Key Legislative Changes Under Emergency Ordinance 156/2024

  • Two main tax systems for businesses: turnover tax and profit tax;
  • Individual rental income tax is 8%;
  • Investment income tax is between 1% and 3%;
  • 10% tax on deposit interest.

Impact on Businesses and Individuals

Businesses will face big tax changes.

They need to adjust their money plans to follow new rules.

For individuals, tax rates on different incomes will change, so they must plan ahead.

Timeline of Implementation

  1. New tax rules start in January 2025;
  2. Full legal changes needed;
  3. Benefits for different sectors might change.

Dealing with these changes needs expert help and a deep understanding of Romania’s tax world.

Dividend Tax Increase: From 8% to 10%

Romanian Tax Reform Dividend Taxation

The Romanian tax system is changing a lot in 2025.

A big change is the dividend tax rate going up from 8% to 10%.

This is a 25% increase for investors and companies in Romania.

This tax reform Romania introduces will impact various taxpayers, including:

  • Corporate entities distributing dividends;
  • Individual investors;
  • Non-resident shareholders.

Key considerations for the new dividend tax regulation include:

  1. The new 10% rate becomes effective from January 1, 2025;
  2. To benefit from the existing 8% tax rate, dividends must be distributed by December 31, 2024;
  3. Health insurance calculations for dividends will reference the new minimum wage of 4,050 lei.
Tax Parameter2024 Rate2025 RateChange
Dividend Tax Rate8%10%+25%
Health Insurance Base3,300 lei4,050 lei+22.7%

Investors and businesses need to plan their dividend strategies carefully.

This is to make the most of the new tax rules in Romania.

Getting advice from a Romanian tax expert can help you deal with these changes well.

Changes in IT, Construction, and Agricultural Sector Tax Benefits

The Romanian fiscal landscape is changing a lot in 2025, mainly for key sectors.

Your tax planning in Romania needs to keep up with new rules for IT, construction, and agriculture.

The government is making big changes.

These will affect income tax updates and tax compliance in many sectors.

Elimination of Income Tax Exemptions

Starting January 2025, big changes will hit tax incentives in key sectors:

  • Software developers will pay 10% income tax.
  • Construction workers will also pay 10% income tax.
  • Agricultural workers will face the same 10% tax rate.

New Pension Insurance Contribution Rules

New rules for pension insurance contributions are coming:

Contribution TypeRateSector Impact
Pension Contribution25%IT, Construction, Agriculture
Health Insurance10%Targeted Sectors
Work Insurance2.25%Employer Contribution

Salary Thresholds and Implications

New salary rules are being set:

  • Construction workers need a minimum salary of 4,582 lei/month.
  • Agricultural workers need a minimum of 4,050 lei/month.
  • Those earning less than 4,300 lei get a 300 lei tax break each month.

Businesses need to check these changes.

They must stay compliant and plan their finances wisely in Romania’s changing tax scene.

2025 Tax News Romania: Major Reform Overview

Tax changes will affect how we handle personal finance and change economic forecasts.

The government is making big updates to the tax code to improve fiscal compliance and support the economy.

Some major changes include:

  • Dividend tax increase from 8% to 10%;
  • Micro-enterprise tax system restructuring;
  • Introduction of new construction sector taxation;
  • Sector-specific tax modifications.

For businesses and individuals, understanding these changes is key.

Tax lawyers in Romania are ready to help.

They will offer detailed advice on how to deal with the new rules.

Reform AreaKey ChangesImplementation Timeline
Corporate TaxationDividend tax increaseJanuary 1, 2025
Micro-Enterprise SystemNew turnover thresholdsJuly 1, 2025
Sector-Specific ReformsTax benefit adjustmentsPhased implementation

Romania wants to cut its budget deficit to 7% of GDP by 2025.

This goal matches what the European Commission suggests.

These changes are important for Romania’s economic growth and better fiscal management.

Micro-enterprise Tax System Overhaul

Romania’s tax reform for 2025 is making big changes to the micro-enterprise tax system.

These updates will change how small businesses handle their taxes and financial planning.

It’s important for entrepreneurs to understand these new rules to stay on top of their taxes.

The Romanian Government is making big changes to tax services for small businesses.

Businesses need to keep up with these new tax rules to stay financially healthy.

New Turnover Thresholds

One big change is the lower annual turnover thresholds:

  • Current threshold: EUR 500,000;
  • New threshold for 2025: EUR 250,000;
  • Projected threshold for 2026: EUR 100,000.

Changes in Qualification Criteria

The new rules make it harder for businesses to qualify as micro-enterprises.

They need to check if they meet the new criteria to stay compliant.

CriteriaPrevious RuleNew Rule
Annual Turnover LimitEUR 500,000EUR 250,000
Consultancy ServicesDisqualifying ConditionRemoved
Management ServicesDisqualifying ConditionRemoved

Small businesses need to quickly adjust to these changes.

Working with tax advisors can help you understand and plan for these changes.

Introduction of Construction Tax in 2025

Romania is introducing a big change for the construction sector in 2025.

A 1% construction tax will be applied to existing buildings on company balance sheets.

This tax is part of Romania’s fiscal policy for 2025.

It aims to bring in more money and make the tax system clearer.

Key aspects of the construction tax include:

  • Applies to all business entities with construction assets;
  • Tax rate set at 1% of the construction’s balance sheet value;
  • Impacts both domestic and foreign businesses with permanent establishments;
  • Implementation date: January 1, 2025.

This tax will affect many sectors, like real estate and construction.

Companies need to check their asset values.

They must also get ready for this new financial duty in Romania’s tax landscape for 2025.

Entity TypeTax ApplicabilityCalculation Basis
Local CompaniesFull Implementation1% of Balance Sheet Value
Foreign EnterprisesPermanent Establishment1% of Romanian Asset Value
Small and Medium EnterprisesProportional Application1% of Qualifying Assets

Businesses should talk to tax experts.

They need to understand these tax changes fully.

This will help them manage their new tax duties well.

VAT Changes and Future Considerations

There are big updates to the VAT system that will affect both businesses and consumers.

These changes in fiscal policy are very important and need to be watched closely.

New VAT rates and digital reporting rules are coming.

Businesses need to get ready for these changes.

They must make sure they follow the rules to avoid any financial problems.

Potential Rate Adjustments

There are talks about changing the VAT rates in Romania.

The exact changes are not clear yet.

But, experts think these changes could affect how businesses price their products.

  • Potential VAT rate increase under consideration;
  • Alignment with EU fiscal policy recommendations;
  • Possible impact on consumer spending.

E-invoicing Requirements

Romania is starting a new digital invoicing system called RO eVAT.

This change will make businesses use electronic invoices.

It will make things clearer and easier for everyone.

SAF-T Implementation

The Standard Audit File for Tax (SAF-T) will soon be a must for businesses.

This change will help Romania’s tax system work better.

It will make tax compliance easier and more transparent.

Digital Tax FeatureImplementation TimelineBusiness Impact
RO eVAT SystemJanuary 2025Mandatory Electronic Invoicing
SAF-T ReportingQ2 2025Enhanced Tax Transparency

Get your business ready for these changes.

Update your digital setup, train your team, and talk to tax experts.

This will help you deal with the new tax rules smoothly.

Minimum Wage Updates by Sector

The 2025 Romanian tax updates change minimum wages in different sectors.

The government has made new rules for construction, agriculture, and food industries.

These changes will affect workers and businesses.

Here are the main updates for each sector:

  • Construction sector: Minimum wage set at RON 4,582;
  • Food and agricultural industry: Minimum wage established at RON 4,050.

The government wants to help workers and support the economy.

These changes will likely change how companies pay their workers.

It might also change how they hire and what they pay.

SectorMinimum Wage (RON)Key Implications
Construction4,582Higher labor costs, possible better work
Agriculture/Food4,050More money for workers, better competition

The 2025 tax changes aim to grow the economy and pay workers fairly.

Companies in these sectors need to plan their budgets and paychecks.

They must follow the new wage rules and stay financially stable.

Businesses should do the following:

  1. Check their current pay scales;
  2. Update their budget plans;
  3. Make sure they meet the new wage rules;
  4. Look at how they pay their workers overall.

Tax Compliance and Reporting Requirements

The Romanian tax system is changing a lot in 2025.

This change will affect how businesses deal with taxes.

The government’s new tax rules will change how companies report their finances and follow the law.

Digital Transformation in Tax Administration

Your business needs to get ready for big changes in tax laws. The main updates include:

  • Mandatory B2B e-invoicing regime fully implemented;
  • Electronic invoice submissions through eFactura platform;
  • Simplified invoicing for small transactions;
  • SAF-T reporting requirements expanded.

Filing Deadlines and Procedures

The tax system in Romania is getting a big update.

Starting in January 2025, businesses will have to follow new rules for electronic reports.

The main changes are:

  1. Mandatory electronic submission of financial statements;
  2. Monthly trial balance preparations;
  3. Specific submission deadlines for different entity types.

Professional Tax Advisory Support

Understanding the new tax rules in Romania can be hard.

 Romanian Tax lawyers and tax consultants are very important.

They help you with digital reporting, e-invoicing, and avoiding fines.

Businesses in Romania need to get ready for these changes.

They should invest in good tax systems and get help from experts.

This will help them adapt well in 2025.

Impact on Foreign Businesses Operating in Romania

The future tax landscape in Romania is set to pose big challenges for foreign businesses.

They will face changes in tax laws in 2025.

It’s vital for them to stay updated on these changes to keep their operations smooth.

Foreign companies need to get ready for big changes in their financial plans.

The new tax rules in Romania will demand careful planning and expert advice.

  • VAT registration requirements have become more stringent;
  • Tax representative obligations are expanding;
  • Dividend tax increased from 8% to 10%;
  • New reporting and compliance mechanisms introduced.

To tackle these challenges, hiring a tax lawyer in Romania is key.

They can help you:

  1. Understand complex tax rules;
  2. Make sure you follow new laws;
  3. Reduce financial risks;
  4. Find the best tax strategies.
Business Impact AreaKey Changes in 2025Potential Risk Level
VAT RegistrationStricter Non-Resident RequirementsHigh
Dividend Taxation10% Tax RateMedium
Compliance ReportingEnhanced Digital ReportingHigh

Businesses that act early will use tax advisory services to deal with these changes.

By keeping up with Romania’s tax changes, foreign companies can stay competitive and financially stable.

Working with Tax Lawyers in Romania

Understanding Romanian tax laws is tough.

With big changes in 2025, knowing how to comply is key.

Businesses and individuals need tax lawyers to guide them.

Romanian law offices help clients deal with tax rules.

When picking a law firm, look for experts in local and global tax laws.

Legal Assistance for Tax Compliance

Tax lawyers in Romania offer vital help:

  • They explain complex tax laws;
  • They create tax-saving plans;
  • They help in tax disputes;
  • They make sure you follow the law.

Professional Tax Advisory Services

Romanian tax lawyers give strategic advice in many areas:

Service CategoryKey Focus Areas
Corporate Tax PlanningLowering tax bills, smart business deals
Individual Tax ConsultingOptimizing personal taxes, global tax rules
Regulatory ComplianceKeeping up with 2025 tax changes

Choose tax lawyers in Romania who are good at handling tax changes.

They should know Romanian tax laws well.

Conclusion

The 2025 tax news in Romania shows a complex fiscal scene.

It demands smart planning.

Tax reforms will affect businesses and people in many areas.

It’s important to be proactive and well-informed about these changes.

This way, you can handle them better.

Understanding these updates means analyzing new tax rates and rules.

The standard VAT rate is 19%, and company taxes vary from 1% to 3% on turnover.

Businesses need to adjust fast to these changes.

Getting help from tax advisors is key in this changing world.

Romania’s economy is expected to grow by 2.5% in 2025.

Knowing the rules can help you avoid financial risks and stay ahead in the market.

As taxes keep changing, being flexible and ready is essential.

Look for expert advice, keep up with new laws, and be open to changing your financial plans in Romania.

FAQ

What are the most significant tax changes in Romania for 2025?

The main changes include a higher dividend tax of 10% from 8%.

There’s also a new construction tax and rules for micro-enterprises.

These changes aim to update Romania’s tax system.

How will the dividend tax increase affect investors and businesses?

The tax hike on dividends will affect both local and foreign investors.

It might change how they invest and manage money.

Companies and investors will need to adjust their financial plans to the new tax rate.

What changes are happening to the micro-enterprise tax system?

The micro-enterprise tax system is changing a lot.

The turnover limits are dropping from EUR 500,000 to EUR 100,000 (in 2026).

Also, a rule about consultancy and management services income is gone, affecting how businesses are taxed.

Are there new VAT requirements for businesses in Romania?

Yes, Romania is introducing e-invoicing and SAF-T reporting.

Businesses must adapt to these digital systems.

They aim to make tax compliance easier and reduce paperwork.

How will the construction tax work in 2025?

A 1% tax will be applied to the value of existing constructions.

This tax will affect many entities, including foreign ones with permanent setups in Romania.

The rules and exemptions will vary based on the entity and construction type.

What changes are affecting foreign businesses operating in Romania?

Foreign businesses will face new VAT rules and changes to tax representative duties.

The dividend and construction taxes will also impact them.

These changes might force businesses to rethink their strategies in Romania.

Are there changes to minimum wage regulations in specific sectors?

Yes, minimum wages are increasing in construction, food, and agriculture.

These changes will affect labor costs.

They might influence how businesses compete and pay their employees.

How can businesses and individuals navigate these tax changes?

It’s wise to talk to a tax lawyer or advisor who knows Romanian tax law.

They can help with compliance, find tax-efficient ways, and explain the new rules.

When do these tax changes take effect?

The tax reforms from Emergency Ordinance 156/2024 will roll out in 2025.

Some changes start right away, while others will be phased in.

It’s important to know when each rule starts.

What is the purpose of these tax reforms?

The reforms aim to update Romania’s tax system.

They want to improve tax collection, follow EU standards, and make the fiscal environment better for businesses and investors.
Finance team reviewing a Romanian RO e-Factura electronic invoice workflow

RO e-Factura Romania 2026: Foreign Company Guide

RO e-Factura in Romania is no longer only a local accounting issue. A foreign company may be affected because it has a Romanian subsidiary, a fixed establishment, a Romanian VAT registration, domestic transactions or Romanian customers. The correct result depends on the company’s VAT status and the transaction—not simply on the country in which the parent company is incorporated.

Key points for 2026:

  • From 1 January 2026, the statutory transmission deadline is generally five working days, subject to the separate legal deadline for issuing the invoice.
  • A Romanian VAT number alone does not necessarily mean that a foreign company is established in Romania.
  • Domestic B2B clearance, reporting by a non-established supplier and invoices to a foreign Romanian-VAT-registered customer must be classified separately.
  • When RO e-Factura is mandatory, a PDF is not a substitute for the validated structured electronic invoice.
  • The operational record should preserve the XML, the Ministry of Finance electronic seal or validation response, submission evidence and any corrected invoice.

This guide updates the existing Atrium article for the 2026 rules and is intended for foreign investors, finance teams, Romanian subsidiaries and non-resident businesses with Romanian VAT exposure. It should be read together with advice on Romanian tax law and, where a foreign entity needs a local fiscal identifier, the guide to obtaining a Romanian NIF tax identification number.

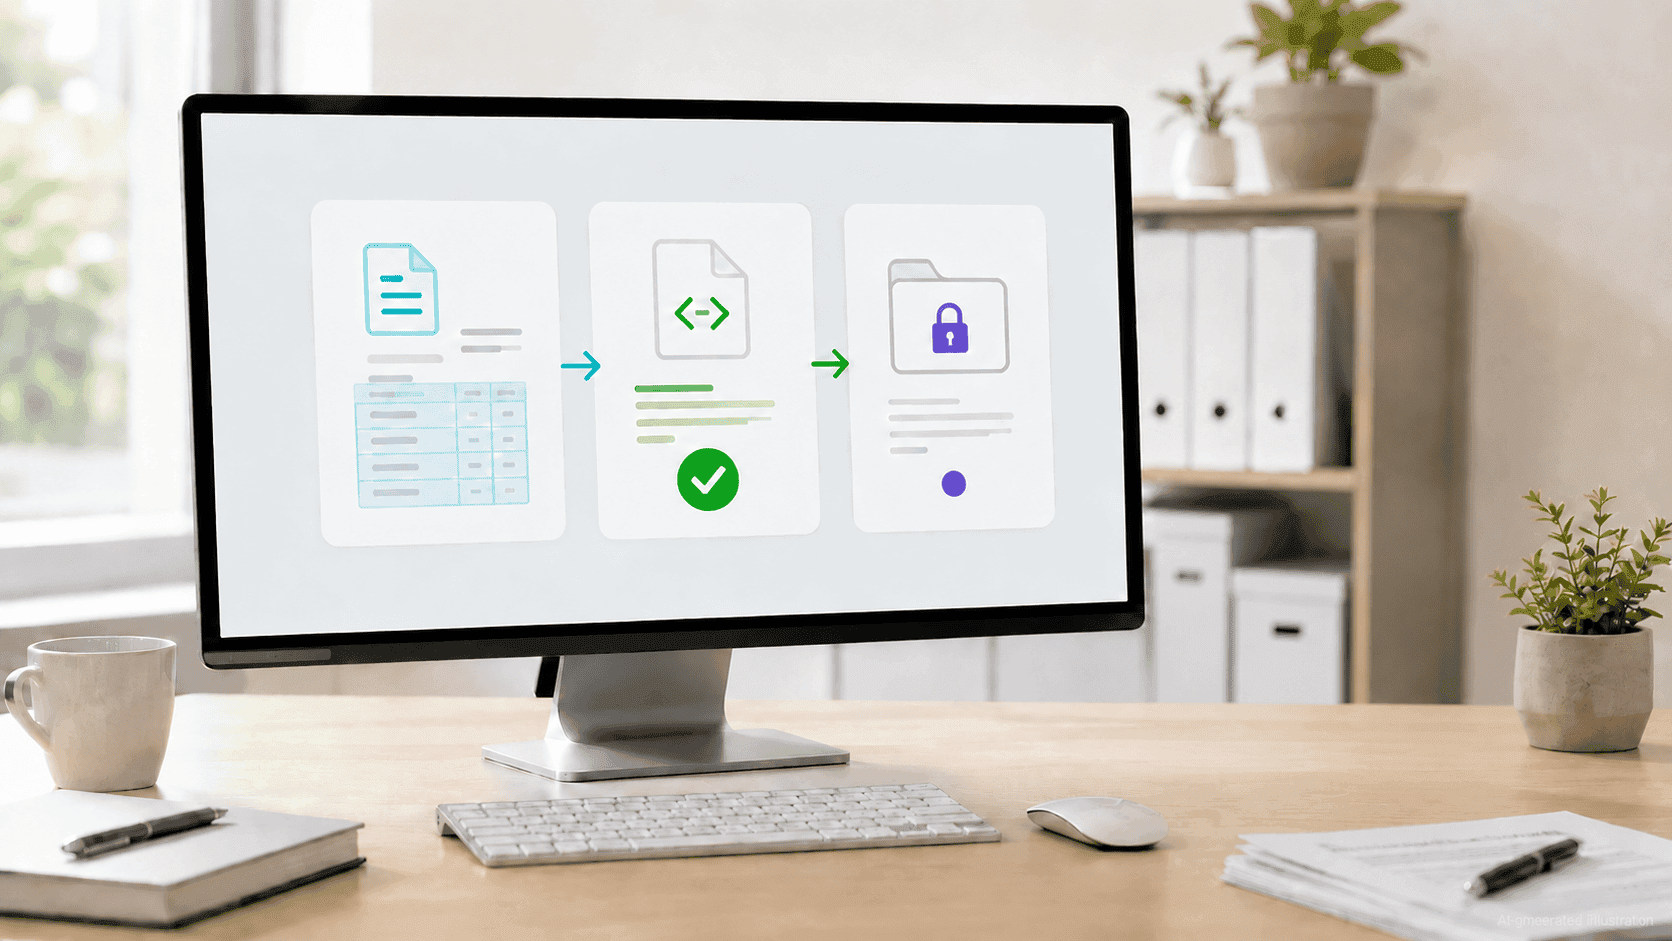
RO e-Factura compliance in Romania for foreign companies
RO e-Factura compliance workflow for companies operating in Romania. AI-generated illustration.

What changed for RO e-Factura in 2026?

The most important operational change is the move from five calendar days to five working days. The change was introduced through Government Emergency Ordinance no. 89/2025, which amended OUG no. 120/2021 and replaced the previous five-calendar-day transmission deadline with a five-working-day deadline effective from 1 January 2026. See also the explanatory summaries published by Contabilul and VATupdate. The deadline runs from the invoice issue date, but it cannot extend beyond five working days calculated from the statutory deadline for issuing that invoice under the Romanian Fiscal Code. Public holidays and the precise date from which the period is calculated should therefore be built into the company’s controls.

2026 pointPractical meaningControl to implement
Five working daysThe transmission period is counted in working days from 1 January 2026, subject to the invoice-issuance backstop.Use a Romanian working-day calendar and escalate before the final day.
Foreign VAT customersA Romanian-established supplier may have reporting duties for domestic invoices issued to a non-established customer registered for VAT in Romania.Separate establishment, VAT registration and invoice-delivery status in customer master data.
Special B2C exceptionsFrom 1 June 2026, Law 88/2026 introduced optional treatment for certain natural persons and specifically listed categories.Do not treat every individual customer record as identical.
Older guidanceMaterials referring to the calendar-day deadline, future 2025 B2C implementation or obsolete registration forms may be outdated.Version-control procedures and use current ANAF forms and legislation.
Scope selector
Which foreign-company profile are you assessing?

Select the closest profile. The explanation below is a screening result, not a substitute for transaction-level VAT analysis.

Romanian subsidiary

A Romanian company making domestic B2B supplies is ordinarily within the mandatory domestic system. Map invoice types, credentials, software and recipient status before go-live.

Does RO e-Factura apply to a foreign company?

There is no reliable yes-or-no answer based only on the existence of a Romanian VAT number. The analysis should identify the supplier, customer, place of supply, establishment used for the transaction, VAT-registration status and invoice category.

A Romanian subsidiary is a Romanian-established taxable person. A foreign company may also have a Romanian fixed establishment if the relevant VAT tests concerning sufficient permanence and human and technical resources are met. By contrast, a foreign company can be registered for Romanian VAT without being established in Romania.

Particular care is required where a foreign company is not established in Romania but holds a Romanian VAT registration. Such businesses should not automatically be analysed under the same mandatory domestic B2B clearance rules that apply to taxable persons established in Romania. Their obligations must be verified separately under the specific provisions applicable to non-established VAT-registered persons and any optional RO e-Factura registration route.

Business situationLikely RO e-Factura treatmentQuestion requiring verification
Romanian subsidiary invoices a Romanian businessDomestic B2B clearance is generally mandatory.Are any statutory exclusions or special invoice rules relevant?
Foreign company supplies through a Romanian fixed establishmentThe entity may be treated as established for the relevant transaction.Is the Romanian establishment actually involved in the supply?
Foreign company has only a Romanian VAT registrationVAT registration alone does not create a Romanian establishment. Any reporting obligations should be assessed separately from the mandatory domestic B2B clearance regime applicable to established taxable persons.What is the place of supply and has the company opted into the system?
Romanian supplier invoices a non-established customer registered for Romanian VATReporting obligations should be analysed under the specific rules applicable from 1 January 2026. Additional commercial transmission arrangements may still be required depending on the recipient’s status and access to the system.Is the recipient participating in RO e-Factura or only VAT-registered?
Export, intra-Community supply or service with place of supply abroadGenerally outside the domestic B2B exchange rule, subject to transaction-specific reporting.Is the VAT classification and evidence supporting the cross-border treatment correct?

Important distinction: an obligation to report invoice data is not always identical to full platform exchange between supplier and recipient. A non-established business should confirm whether it is reporting a domestic transaction, voluntarily registered in RO e-Factura or subject to the domestic clearance route because of a Romanian establishment.

How does the electronic invoice flow work?

The invoice is prepared as structured data compliant with the Romanian semantic model, based on the European e-invoicing standard. It is transmitted through the Ministry of Finance infrastructure, commonly through SPV-integrated software or an authorised technical solution. The system validates the file. If validation succeeds, the electronic seal is applied and the validated file becomes the system invoice. If it fails, the issuer receives an error response and must correct and resubmit it.

Invoice flow
From accounting data to defensible archive

Select a control point to see what the finance or IT team should retain.

Create structured XML

Generate the invoice from accurate supplier, customer, VAT and line-item data using the current RO_CIUS technical rules.

The official platform makes files available for download for a limited operational period. This is not a substitute for the company’s own legally compliant archive. The archive should allow the original XML, seal or validation status, readable representation, correction trail and accounting entry to be matched.

Technical specifications, validators and official web applications are published through the Ministry of Finance technical information page and the RO e-Factura web applications page.

Which transactions are in scope?

The Romanian rules cover several legally distinct streams: B2B, B2G and B2C reporting, as well as particular reporting obligations for non-established persons. Companies should not use a single ERP flag called “Romanian customer” as a substitute for the legal analysis.

The B2C reporting regime introduced for suppliers established in Romania should not automatically be assumed to apply to every non-resident supplier. For foreign businesses without a Romanian establishment, the legal position should be verified separately based on the applicable provisions and transaction structure.

Transaction2026 starting positionOperational note
Domestic B2B between persons established in RomaniaMandatory platform exchange, unless a statutory exclusion applies.The validated XML is the legally relevant electronic invoice.
B2G invoice within the statutory regimeMandatory according to the public-procurement and e-invoicing rules.Check public authority identifiers and contract references.
B2C invoice issued by an established supplierReporting is generally mandatory, with specific 2026 exceptions.The consumer does not need SPV access for the commercial invoice.
Domestic transaction by a non-established VAT-registered supplierA reporting obligation may apply; optional system registration changes the mechanics.Confirm current registration form and recipient-delivery channel.
Export or intra-Community supplyGenerally outside the domestic B2B exchange obligation.Retain evidence supporting the VAT treatment and destination.
Simplified invoice or other statutory exceptionTreatment depends on the specific legal exception.Do not infer exclusion merely because the amount is small.

How is the five-working-day deadline calculated?

From 1 January 2026, the invoice must generally be transmitted within five working days from the issue date, but no later than five working days after the last legal date on which the invoice should have been issued. The day of the triggering event, weekends and Romanian public holidays can affect the calculation under the applicable time-computation rules.

A delayed invoice issue date does not automatically postpone the transmission deadline. Where the invoice is issued after the statutory issuance deadline under Article 319 of the Romanian Fiscal Code, the five-working-day transmission period must be assessed by reference to the legal issuance deadline rather than the late issuance date. This backstop is also explained in the 2026 deadline summary.

Deadline control
A working-day clock needs four checks

Select a card to see the control that prevents a false deadline.

Confirm issue date

Use the date actually stated on the invoice and reconcile it with the accounting event. Backdating or delayed batch creation can create an immediate compliance risk.

For example, if an invoice is issued on a Monday and there is no public holiday, Tuesday is ordinarily the first working day and the following Monday is the fifth. This is only an illustration: the statutory invoice-issuance deadline and Romanian public holidays must also be checked.

What happens if an invoice fails validation?

A technically rejected file has not completed the required process. The response should be triaged immediately: identify whether the problem concerns syntax, master data, tax codes, totals or a business-rule conflict; correct the source data; regenerate the XML; resubmit it; and preserve both the failed and successful responses.

A successfully communicated invoice cannot simply be “returned” inside the system. Commercial objections should be handled separately, and corrections should follow Article 330 of the Romanian Fiscal Code. The corrective document must itself be transmitted when the RO e-Factura obligation applies.

What penalties and audit risks should foreign companies consider?

The penalty analysis depends on the legal obligation that has been breached. Late reporting can attract fixed fines by taxpayer category. For mandatory domestic B2B exchange, issuing or accepting an invoice outside the system can trigger a percentage-based sanction. The 15% sanction should not be applied mechanically to every cross-border or non-resident scenario without first confirming that the relevant statutory route covers the transaction and party.

The applicability of the 15% sanction should always be assessed by reference to the specific statutory obligation governing the transaction, including the supplier’s establishment status and the legal route under which the invoice was required to be transmitted.

RiskPossible consequencePreventive evidence
One or more late invoices in a calendar monthGenerally RON 5,000–10,000 for large taxpayers; RON 2,500–5,000 for medium taxpayers; RON 1,000–2,500 for other legal persons and individuals.Deadline dashboard, submission timestamps and exception log.
Mandatory domestic B2B invoice issued outside the systemA sanction equal to 15% of the total invoice value may apply to the issuer under the relevant rule.ERP block preventing off-system finalisation of in-scope invoices.
Recipient records an in-scope domestic B2B invoice received outside the systemA corresponding 15% sanction may apply to the recipient, subject to the statutory conditions.Accounts-payable validation against the system record.
Validation failure left unresolvedThe invoice may remain untransmitted and become late.Error queue, named owner, retry log and successful response.
Wrong establishment or customer classificationIncorrect platform route, missing report or duplicate delivery.Documented VAT and establishment decision tree.
Control map
Where implementation most often fails

Select a risk to see the corresponding control.

Wrong customer status

Maintain separate fields for country, Romanian VAT number, establishment status, customer type and participation in RO e-Factura. One “foreign” flag is not enough.

Implementation checklist for a foreign company

  1. Map the Romanian footprint. Identify subsidiaries, branches, fixed establishments, VAT registrations and fiscal representatives.
  2. Classify transaction flows. Separate domestic B2B, B2G, B2C, exports, intra-Community supplies, local reverse-charge cases and other cross-border services.
  3. Confirm access and authority. Verify SPV access, qualified certificates, mandates and the persons authorised to submit or retrieve files.
  4. Update master data. Record establishment status, Romanian VAT identifiers, customer type and system-participation status separately.
  5. Test XML generation. Validate tax codes, units, discounts, advance invoices, credit notes, currency and rounding rules.
  6. Build deadline monitoring. Use Romanian working days, identify the statutory issue-date backstop and prevent submission only on the final day.
  7. Create an error workflow. Route rejected files to a named owner and require documented resubmission.
  8. Control incoming invoices. Reconcile accounts payable with RO e-Factura where domestic B2B exchange is mandatory.
  9. Archive the evidence. Preserve XML, seal or response, readable copy, corrections and submission logs under the applicable accounting and tax-retention rules.
  10. Review changes. Monitor the official Ministry of Finance RO e-Factura hub, current legislation and ANAF technical announcements.

Official registration and verification resources

At the time of publication, ANAF documentation refers to Form 081 for the optional register, Form 082 for the mandatory register and Form 083 for certain non-resident operators. Companies should verify the current ANAF form catalogue before implementation, as registration procedures and form numbering may change over time.

At the time of publication, Form 083 is generally used by certain non-established operators wishing to opt into RO e-Factura. Companies should verify the current ANAF requirements before filing because registration procedures may change.

Use the official ANAF forms catalogue and the ANAF online registers. For the governing framework, consult the current consolidated text of Government Emergency Ordinance no. 120/2021, together with subsequent amendments including Law no. 88/2026.

Need a transaction-specific RO e-Factura review?

A focused review can determine whether a foreign company is established, merely VAT-registered or subject to a separate domestic reporting route, and translate that conclusion into an implementable invoice workflow.

Book a Consultation

Frequently asked questions

Does a Romanian VAT number make a foreign company established in Romania?

No. VAT registration and establishment are separate concepts. A fixed-establishment analysis considers permanence and appropriate human and technical resources, as well as whether that establishment is involved in the transaction. A Romanian VAT registration obtained through direct registration or fiscal representation does not in itself create a Romanian fixed establishment for VAT purposes.

Are all invoices involving a foreign company reported through RO e-Factura?

No. The result depends on the supplier, customer, place of supply, establishment status, Romanian VAT registration and invoice category. Exports and intra-Community supplies are generally outside the domestic B2B exchange rule, although other reporting obligations may apply.

What is the RO e-Factura deadline in 2026?

From 1 January 2026, the general transmission deadline is five working days from issue, but no later than five working days calculated from the statutory deadline for issuing the invoice. Romanian public holidays and the applicable time-computation rules must be included.

Is a PDF invoice sufficient?

Not where mandatory RO e-Factura exchange applies. The structured XML validated through the system and accompanied by the Ministry of Finance electronic seal is the legally relevant electronic invoice. A PDF may remain useful as a readable copy.

Can a recipient reject an invoice in RO e-Factura?

The system invoice cannot simply be returned. The recipient may communicate objections, while any correction should follow Article 330 of the Fiscal Code and be transmitted through RO e-Factura when the obligation applies.

What should a company do after a validation error or platform problem?

Preserve the response and technical logs, identify and correct the error, resubmit promptly and retain the successful confirmation. A company should not assume that a technical issue automatically extends the statutory deadline; any official unavailability procedure should be checked on the facts.

This article provides general information on Romanian electronic invoicing and tax compliance. The result depends on the transaction, place of supply, establishment, VAT status, invoice type, technical implementation and legislation in force. It does not replace legal or tax advice on a specific invoice flow.

AI Notice: AI-assisted content, reviewed and approved by a qualified Romanian lawyer.

What are the legal grounds for contesting an administrative act

What are the legal grounds for contesting an administrative act

In Romania, people and businesses can challenge decisions made by government bodies.

The Law on Administrative Disputes sets the rules for this.

It helps protect your rights if you think a decision was unfair.

Knowing how to contest an administrative act is key.

It helps keep public actions legal and fair.

This way, you can defend your rights effectively.

legal grounds administrative act Romania

Key Takeaways

  • The Law on Administrative Disputes in Romania allows for the judicial review of administrative acts to protect citizens’ rights and ensure the legality of public administration activities.
  • Individuals and legal entities can initiate administrative proceedings if they believe an administrative act has violated their rights or direct personal interests.
  • Contesting administrative acts is a crucial mechanism for holding public authorities accountable and ensuring the legality of their decisions.
  • The legal grounds for challenging administrative acts in Romania include lack of competence, procedural violations, and violation of substantive law.
  • Seeking legal assistance from specialized administrative lawyers can help navigate the complexities of administrative litigation and increase the chances of success.

Understanding Administrative Acts and Their Legal Framework

In Romania, the rules for administrative acts come from the Law on Administrative Disputes and the Administrative Code.

These laws help us understand what administrative law is and how it works in the country.

Definition and Scope of Administrative Acts

Administrative acts are decisions made by public bodies that impact people’s rights or duties.

They can be orders, decisions, permits, or licenses.

Romania’s legal system has two types: normative acts that set rules and individual acts that solve specific problems.

Key Elements of Administrative Law in Romania

  • Principle of Legality: Public bodies must follow the law and stay within their legal powers.
  • Principle of Proportionality: Decisions should match the goal they aim for, balancing public and individual interests.
  • Right to Legal Protection: People and groups can challenge decisions in court or through other legal means.

Role of Public Authorities in Administrative Decisions

Public bodies like ministries and local governments are key in making administrative acts.

They must follow legal steps and act fairly, ensuring transparency and respect for the law.

Their actions can be reviewed in court to make sure they follow the law and protect everyone’s rights.

administrative law romania


Legal Grounds Administrative Act Romania

In Romania, the rules for challenging an administrative act are based on constitutional rightsdue process, and the rule of law.

These acts are the main way public authorities act.

They can be contested on several important grounds.

One reason to challenge an administrative act is if it breaks the law or doesn’t follow the right procedures.

This could happen if the wrong authority makes the act or if the facts are wrong.

The Administrative Court of Romania can decide if an act is legal. If not, they can cancel or change it.

People can also challenge acts made by higher authorities.

This gives them a chance to fight government actions that go against their rights or due process.

Key FactsData
Administrative acts as the main legal form of public administrationAdministrative acts are the main legal form of the activity of public administration authorities.
Building permits as individual administrative actsA building permit is an individual administrative act that produces legal effects as envisaged by the issuing public authority.
Administrative operations vs. administrative actsAdministrative operations (notices, agreements, minutes of establishment) are necessary steps for issuing administrative acts but do not produce legal effects themselves.
Court cases mentioning the exception of illegalityIn the last years (for ex. January 2016 – October 2021), there have been 985 court cases where the exception of illegality was mentioned in Romania.
Areas where the exception of illegality is raisedThe predominant matters where the exception of illegality is raised are urban planning procedures and administrative-fiscal procedures according to the findings from the website www.Rolii.ro.

Knowing how to challenge administrative acts in Romania helps protect rights and ensures fairness.

It allows people to stand up against government actions that don’t follow the law.

administrative law romania

Fundamental Principles of Administrative Dispute Resolution

In Romania, the way we handle disputes with the government is based on key principles.

These ensure everyone’s rights are protected and government decisions are fair.

The main principles are the rule of law, proportionality, and the right to legal defense.

Principle of Legality

The rule of law means all actions by government must follow the law.

This makes sure government decisions are based on solid legal ground.

It also ensures these decisions don’t go beyond what the law allows.

Principle of Proportionality

The principle of proportionality says government actions must match their goals.

These actions should not unfairly restrict people’s rights.

Any limits must be justified and needed to serve a public interest.

Right to Legal Protection

The right to legal protection lets people challenge unfair government decisions in court.

This gives citizens a fair chance to have their say against government actions.

It protects against decisions that are not lawful or fair.

By following these principles, Romania’s dispute resolution process aims to balance government and individual rights.

It promotes transparency, accountability, and the rule of law.

PrincipleDescription
LegalityAdministrative acts must comply with relevant laws and regulations.
ProportionalityAdministrative actions should not excessively limit individual rights.
Right to Legal ProtectionIndividuals can contest unfavorable administrative decisions in courts.

Procedural Requirements for Contesting Administrative Acts

Challenging administrative acts in Romania has specific steps to follow.

These steps are outlined in the laws about administrative actions.

They make sure the process is fair and open.

To challenge an administrative act, you must file a complaint on time.

The Law on Administrative Disputes (No. 554/2004) sets these deadlines.

Missing these deadlines can mean your case is dismissed.

You also need to include all the documents that support your claim.

This might be copies of the act you’re challenging, proof of harm, and other important papers.

It’s key to follow these rules to make your case valid.

When you submit your complaint, you must do it the right way.

This could mean sending it directly to the Administrative Court or following other steps set by the authorities.

Usually, you must try to solve the issue through administrative channels first.

This means appealing the decision through the right channels before going to court.

But, there are exceptions based on the law.

  1. File a complaint within the statutory deadlines set by the Law on Administrative Disputes (No. 554/2004)
  2. Provide the necessary documentation to support your claim, including copies of the contested administrative act and evidence of harm or violation
  3. Follow the proper submission protocols for contesting administrative acts, which may involve direct filing with the Administrative Court or additional procedures
  4. Exhaust administrative remedies before seeking judicial review, unless exceptions apply under the law

Following these steps ensures your challenge is handled correctly.

It respects the legal framework and rules of administrative proceedings in Romania.

Time Limits and Filing Procedures

Understanding time limits and filing procedures is key when dealing with administrative acts in Romania.

These rules are vital for challenging decisions fairly and efficiently.

They help make sure the judicial review process works well.

Statutory Deadlines for Filing Complaints

In Romania, you usually have 30 days to contest an administrative act after you’re notified.

Public prosecutors get 60 days.

Remember, these deadlines can’t be changed by anyone involved.

Documentation Requirements

To challenge an administrative act, you need a few things.

These include the decision you’re contesting, any evidence that supports your claim, and a power of attorney if you’re represented.

It’s important to gather and submit all these documents correctly.

Submission Protocols

You can file a complaint against an administrative act with the right court.

You can do this in person, by mail, or even by recording it at the court.

This makes it easier for people to seek judicial review administrative acts and legality administrative decisions.

Understanding how to challenge administrative acts in Romania is complex.

You need to know the time limits, what documents are needed, and how to submit them.

Following these rules helps individuals and groups exercise their rights and get the judicial review they need.

Rights and Obligations of Parties in Administrative Disputes

In Romania, those in administrative disputes have clear rights and duties.

These rules help make sure the process is fair and open.

If you’re challenging an administrative act, you can speak up, see the case files, and share evidence.

Public authorities must give out important documents and explain their decisions.

This makes sure public actions are clear and fair. Also, others who really care about the outcome can join the case.

Rights of PartiesObligations of Parties
  • Right to be heard
  • Access to case files
  • Right to present evidence
  • Provide relevant documents
  • Justify administrative decisions
  • Participate if direct interest is established

These rules help keep the dispute resolution process fair and balanced.

They follow the public administration law in Romania.

Grounds for Administrative Act Contestation

In Romania, there are many reasons to contest administrative acts.

These include lack of authority, breaking rules, and not following the law.

These reasons help keep the government in check and protect people’s rights.

They make sure the government’s actions can be reviewed in court.

Lack of Competence

One reason to contest an act is if the wrong person made it.

This happens when someone without the right to do so issues a decision.

Or, if the person who signed it didn’t have the power to do so.

Procedural Violations

Another reason is if the act was made without following the proper steps.

This includes not giving enough notice, not consulting the public, or not getting the facts right.

Violation of Substantive Law

Acts can also be challenged if they go against the law or are too broad.

This includes if they contradict higher laws or don’t follow important principles like the right to be heard.

These grounds for contestation are key in Romanian law.

They let citizens review government decisions in court.

This helps keep the government accountable and protects people’s rights.

It’s important for a fair and effective administrative system.

Role of Administrative Courts

In Romania, administrative courts are key in keeping the law and ensuring fair process in government actions.

They can check if government decisions are legal. If not, they can cancel these decisions, ask for new ones, or give money to those affected.

Their rulings are final and must be followed, showing how important they are.

The Supreme Court of Romania can also look at these decisions, adding more checks and balances.

These courts protect people and businesses from government mistakes or unfair actions.

Working with the People’s Advocate, they make sure everyone follows the law and gets a fair hearing.

FAQ

What are the legal grounds for contesting an administrative act in Romania?

In Romania, you can challenge an administrative act if it breaks the law or the rules of procedure.

You can also contest it if the authority that made it wasn’t supposed to. Or if the facts were not correctly established.

What is the legal framework for administrative acts in Romania?

Romania’s laws for administrative acts are based on the Law on Administrative Disputes and the Administrative Code.

These laws ensure acts are legal, fair, and protect citizens’ rights. Public bodies must follow these rules when making decisions.

What are the fundamental principles of administrative dispute resolution in Romania?

In Romania, resolving administrative disputes follows three main principles.

First, acts must follow the law.

Second, actions should be fair and not overly limit rights.

Third, everyone has the right to go to court if they disagree with a decision.

What are the procedural requirements for contesting administrative acts in Romania?

To challenge an administrative act in Romania, you must follow certain steps.

You need to file your complaint within a set time, provide all necessary documents, and follow the right steps.

The Administrative Court of Romania handles these disputes, and you must try to solve the issue first before going to court.

What are the time limits and filing procedures for contesting administrative acts in Romania?

You have 30 days to challenge an administrative act in Romania after you’re told about it.

Public prosecutors have 60 days.

You’ll need to include the act you’re challenging, evidence, and a power of attorney if you have a lawyer in Romania.

You can file your complaint in person, by mail, or by recording it at the court.

What are the rights and obligations of parties in administrative disputes in Romania?

In administrative disputes in Romania, both sides have rights and duties.

You have the right to be heard and to see your case files.

Authorities must give you the documents you need and explain their decisions.

Other people can join the case if they have a direct interest in it.

On what grounds can administrative acts be contested in Romania?

You can challenge an administrative act in Romania for several reasons.

If the authority that made it wasn’t allowed to, if there were mistakes in the process, or if the act goes against the law.

These are the main reasons.

What is the role of administrative courts in Romania?

Administrative courts in Romania are key in checking if administrative acts are legal.

They can cancel acts that are not lawful, ask authorities to make new ones, or give damages.

Their decisions are final, and the Supreme Court can review them if there’s a legal issue.

What is an administrative act under Romanian law?

An administrative act in Romania is a legal document issued by a public authority that creates, modifies, or terminates legal rights and obligations.

These acts are subject to administrative law and can be contested if they violate an individual’s rights or interests.

Romanian law provides specific grounds for challenging such acts, ensuring that public authorities operate within the bounds of legality and respect citizens’ rights.

What are the main legal grounds for contesting an administrative act in Romania?

The primary legal grounds for contesting an administrative act in Romania include:

1. Lack of competence of the issuing authority

2. Violation of legal procedures in adopting the act

3. Breach of substantive law

4. Abuse of power

5. Violation of the principle of proportionality

6. Failure to state reasons or insufficient reasoning

7. Illegality of the act’s content

8. Infringement of fundamental rights and freedoms.

These grounds are established by Romanian law and case law, and can be invoked when seeking to appeal an administrative act.

How can I contest a tax decision in Romania?

To contest a tax decision in Romania, you should follow these steps:

1. Review the decision carefully to identify potential grounds for contestation

2. File a written appeal with the tax authority that issued the decision within 45 days.